Investing for your pension, with a tax refund.
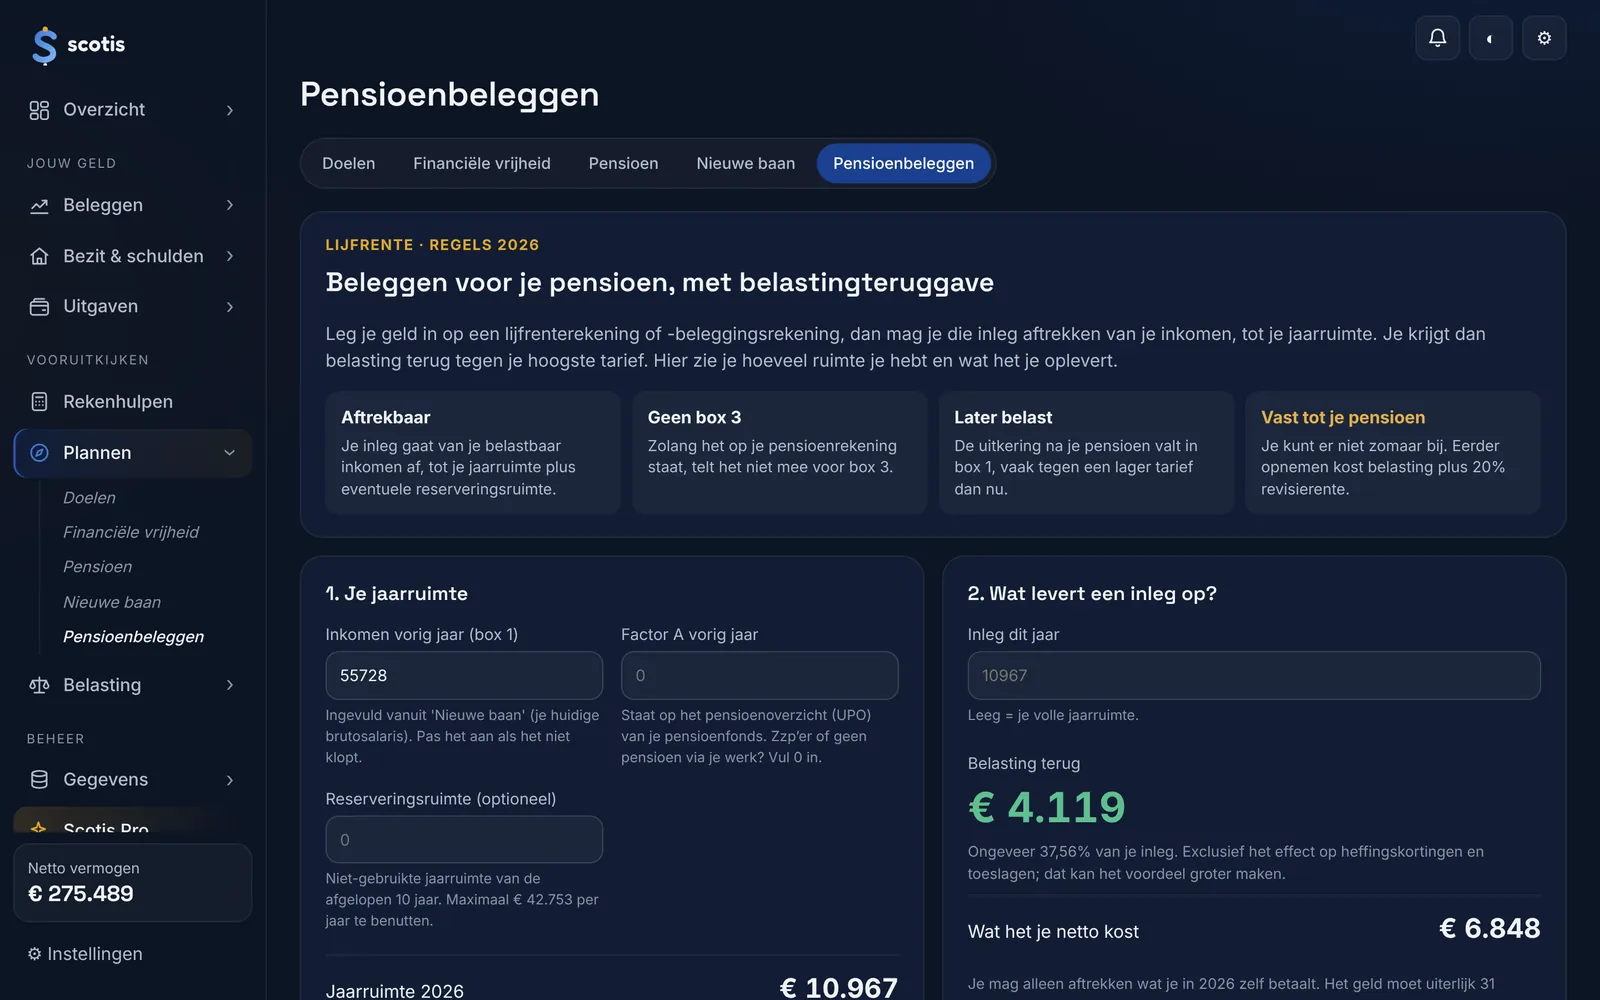
Your jaarruimte (annual allowance for tax-deductible pension saving) for 2026, how much tax you get back when you pay into a lijfrente (pension savings) account, and a worked example up to retirement, compared with regular investing.
What you can do with it
Your jaarruimte
Calculated using the 2026 rules: 30% of your income above the AOW offset (AOW-franchise), minus the pension you build up through work (factor A). Plus your reserveringsruimte (catch-up allowance) from the past 10 years.
What you get back
The tax refund at your own rate, and what the contribution costs you after tax. You can only deduct what you pay before 31 December.
Pension investing or regular investing
A worked example up to your AOW age: your pension pot after tax on the payouts, compared with regular investing under Box 3. With the downsides included: the money is locked until you retire.
Frequently asked questions
What is jaarruimte?
The amount you may put into your pension with a tax benefit. In 2026 it is 30% of your income above the AOW threshold, minus 6.27 times your factor A.
What is reserveringsruimte?
Jaarruimte you did not use over the past 10 years. You may still use it.
Until when do I need to contribute?
You can only deduct what you pay before 31 December of that year.
Updated on 7 November 2026.
Read next
Scotis gives information and worked examples using your own numbers, not financial or tax advice.
Try it with the demo first.
Click around with the numbers of a sample household. If you like it, start with your own numbers.
Try the demo